
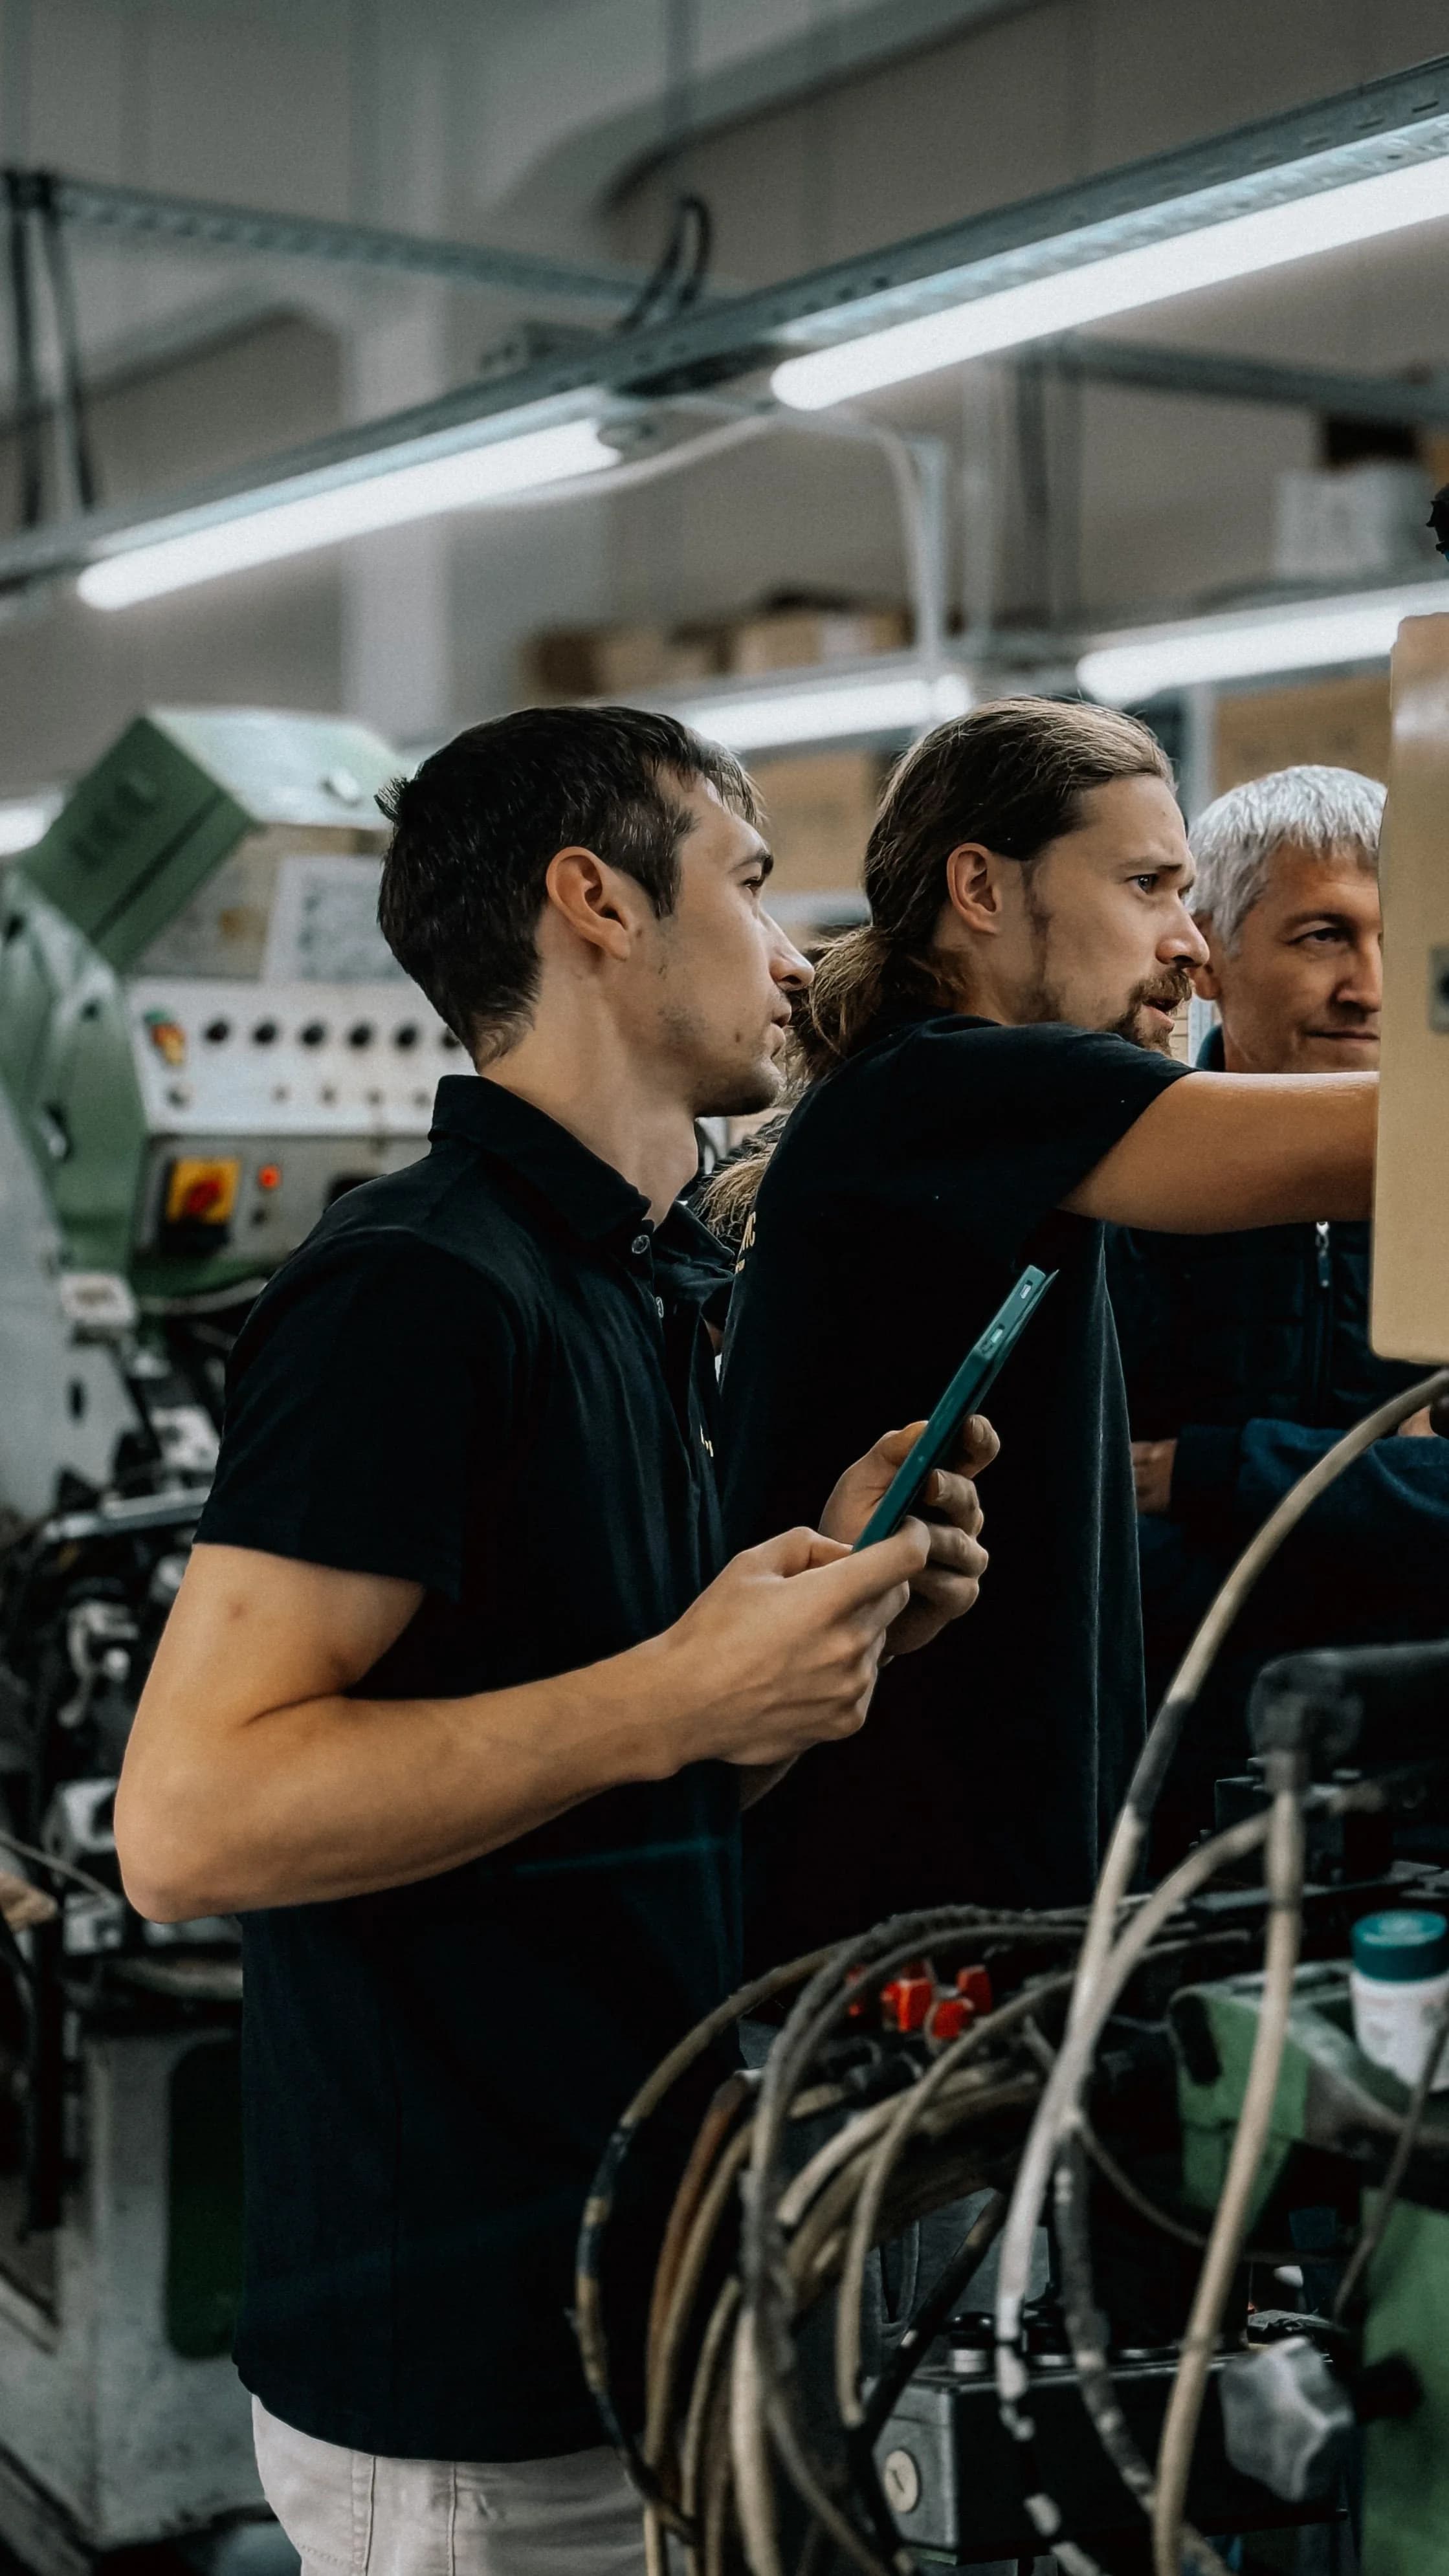
Accurit sector expertise
Accounting for Manufacturing Businesses in Malta
Job costing and stock valuation, so you know which lines actually make money once labour and materials are counted.
The sector, plainly
In manufacturing the interesting number is never the sales figure. It is what a unit costs to make once materials, labour and machine time have all been counted. Most small manufacturers know their revenue per product precisely and their cost per product approximately, which is how a line can stay busy for years without earning anything.
The pressure points
Where manufacturing businesses struggle
Cost per unit known only roughly
Materials get tracked closely and labour gets estimated, which is enough to price a job and not enough to know whether it paid.
Work in progress left out
Part-finished goods on the floor at month-end are real value, and omitting them distorts both stock and profit.
Overhead spread evenly
Fixed costs shared equally across products flatter the slow lines and penalise the fast ones, hiding where money is made.
Our approach
How we work with the sector
Job costing built from actuals
Materials, labour and machine time recorded against the job, so cost per unit comes from what happened rather than an estimate.Stock and work in progress valued properly
Raw materials, part-finished goods and finished stock counted and valued separately at each period end.Overhead allocated on a basis that reflects use
Fixed costs attributed by whatever actually drives them, rather than split evenly for convenience.
The outcome
Here’s what changes for manufacturing businesses.
A cost per unit you can defend
A figure you can quote from, price against and challenge, because it was built from recorded activity.
The lines worth keeping
Product-level profitability after a fair share of overhead, which often reorders what a business thought its best lines were.
Stock figures that hold up
Inventory and work in progress valued on a consistent basis, so the year-end result is not moved by a guess.
COMMON QUESTIONS
Manufacturing questions
Can you tell me what a unit actually costs to make?
Yes. Materials, labour and machine time are recorded against the job, so the cost per unit comes from what happened rather than an estimate.
How is stock valued?
Raw materials, work in progress and finished goods are counted and valued separately at each period end.
How do you split overheads between product lines?
By whatever actually drives them — machine hours, floor space, labour — rather than an even split for convenience.
Continue exploring
Related expertise
Services this sector relies on
Neighbouring sectors we work in
Ready to talk?
Let’s discuss manufacturing for your business
Book a free consultation with our team, or send us a message and we will get back to you.